Quick answer. Melbourne and Victorian businesses can finance new and used equipment through structures such as chattel mortgage, hire purchase, finance lease and rental. Tradie Finance arranges these through a panel of bank and non-bank lenders, assessed on the business, the equipment and the borrower’s circumstances. Approval and terms are subject to lender criteria.
Equipment finance for Melbourne and Victorian businesses
Melbourne’s trades and contracting sector runs on equipment: excavators and skid steers on civil and residential sites, forklifts and racking in warehouses, commercial kitchen fit-outs, workshop machinery, compressors, generators and specialist tools. Most of it costs more than a business wants to pay for out of cash flow in one hit, and most of it earns its keep over several years. Equipment finance spreads the cost across that earning life.
Tradie Finance is a broker, not a lender. We arrange equipment finance for businesses in Melbourne, regional Victoria and Australia-wide through a panel of bank and non-bank lenders. You do not need a local Tradie Finance office to apply. Applications and document collection can be handled remotely, while eligibility still depends on the lender’s criteria, the asset, the business and the borrower’s circumstances. The structure below applies wherever the business is based. Our equipment finance page covers the full national picture; this page focuses on what Melbourne and Victorian operators tend to ask about.
What equipment can be financed?
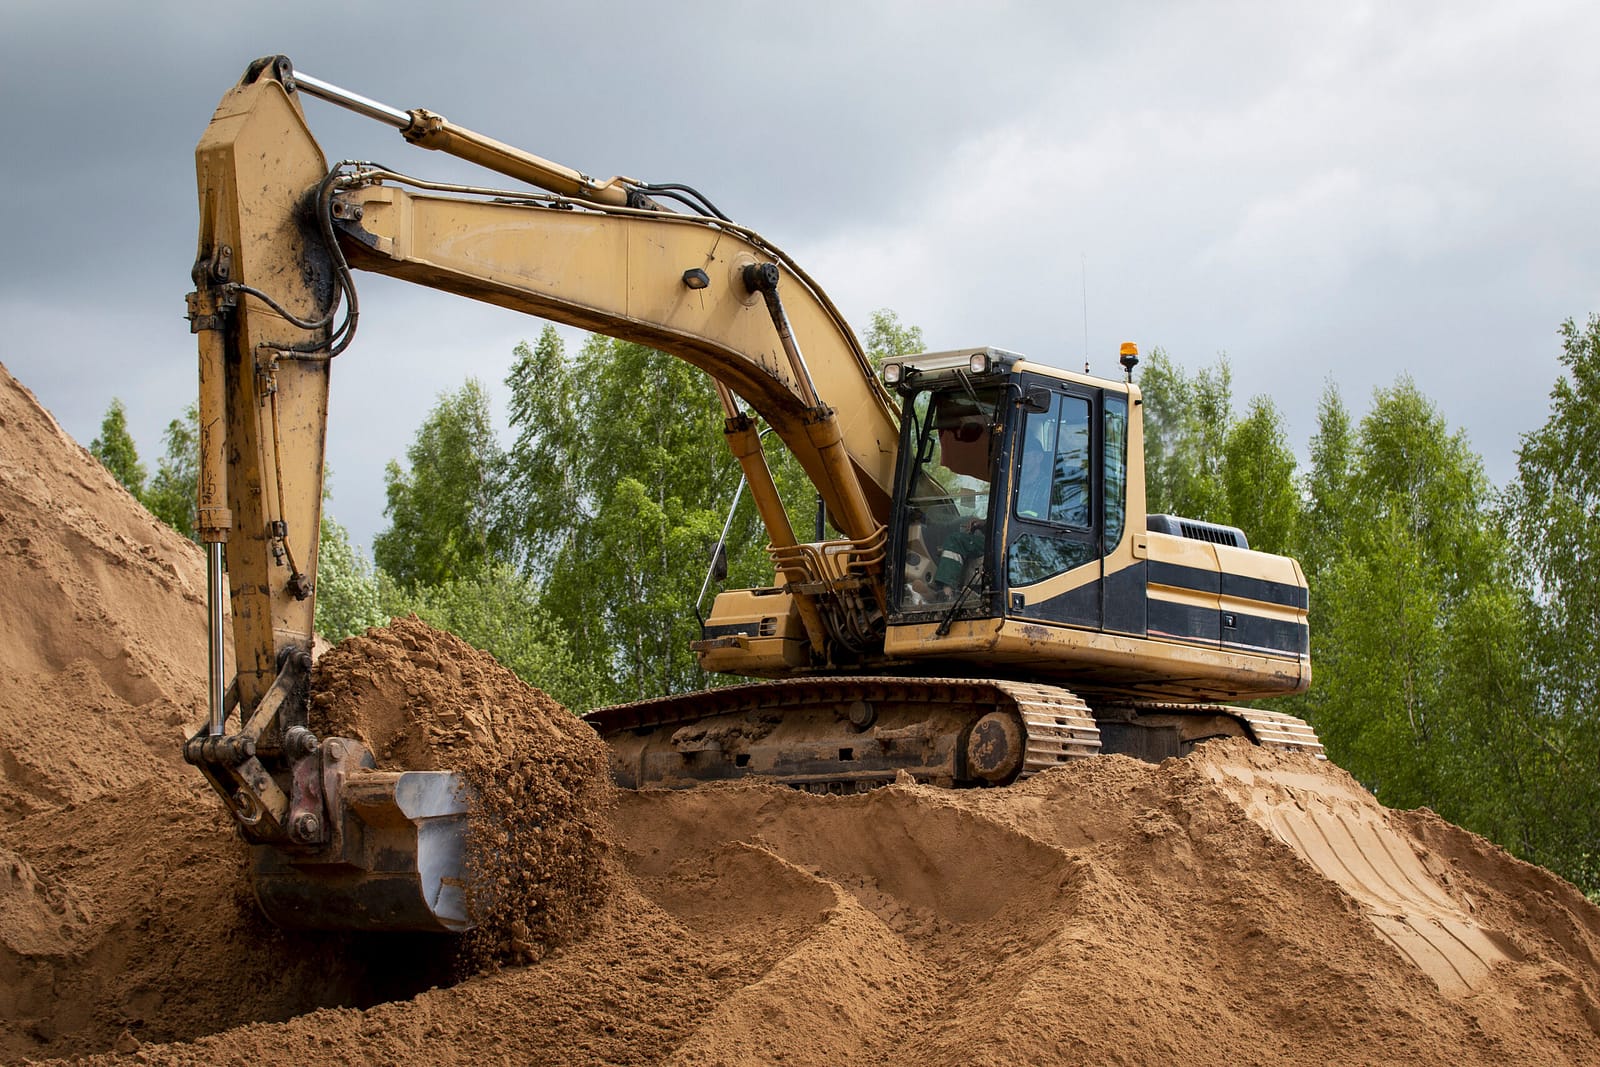
Construction and civil. Excavators, loaders, rollers, trenchers and attachments are commonly financed against the machine itself. See excavator finance and earthmoving equipment finance for detail on how lenders view age, hours and resale value.
Workshop, trade and manufacturing. CNC and fabrication machinery, welders, compressors, press brakes and specialist tooling. Lenders generally want a clear invoice or quote, a serial or identification number, and evidence the equipment will be used in the business.
Warehousing, logistics and hospitality. Forklifts, pallet racking, coolrooms, commercial ovens and fit-out equipment. Items that are fixed to premises or have little resale value can attract tighter treatment, so it is worth raising early.
New or used. Both new and used equipment can be financeable, subject to lender and asset criteria. Used equipment is assessed on age, condition and resale evidence; see used equipment finance.
Which finance structure suits which purchase?
The structure affects ownership, tax treatment and cash flow, so it is worth choosing deliberately rather than taking the first one offered.
Chattel mortgage. You own the equipment from day one and the lender takes security over it. Often used for owner-operators and businesses that want the asset on their own books. See chattel mortgage.
Commercial hire purchase. The lender owns the equipment until the final payment, then ownership passes to you. See commercial hire purchase.
Finance lease and rental. You pay to use the equipment, with options at the end of the term that depend on the agreement. Suits equipment that dates quickly. See finance lease and equipment leasing.
Tax and GST outcomes differ between structures and depend on the business’s circumstances, so confirm the treatment with your accountant before choosing.
How lenders assess a Victorian equipment application
Lenders look at the same core things regardless of state: how long the business has been trading, its financial position and cash flow, the borrower’s credit history, the asset being financed and how much deposit or equity is involved. Established businesses with full financials generally have the widest choice. Newer businesses and those with limited documentation can still be considered by some lenders, but options narrow and terms vary. Every application is subject to the lender’s serviceability and credit assessment.
Your repayment estimate for a particular purchase can be worked through in our equipment finance calculator. It gives an estimate only and is not a quote.
Equipment finance elsewhere
If you operate in South East Queensland, see our Brisbane equipment finance page. For all other locations, start from the main equipment finance page.
Ready to talk equipment finance?
Tell us what you are buying, roughly what it costs and how the business is set up. We will tell you which structures and lenders are worth approaching before anything is lodged.
Frequently asked questions
Do I need to be near a Tradie Finance office?
No. Tradie Finance is a broker that arranges equipment finance for Melbourne and Victorian businesses remotely, through a panel of bank and non-bank lenders. Applications, documents and communication are handled online and by phone, and lender criteria rather than your location determine the options available.
Can I finance used equipment in Victoria?
Yes, in many cases. Lenders assess used equipment on its age, condition, hours or kilometres and resale evidence, and may require a valuation or inspection. Older or specialised items can narrow the lender pool, and terms vary by lender and by asset.
What documents will I need?
Usually photo ID, a quote or invoice for the equipment, business details including your ABN, and evidence of income such as financial statements or bank statements. Requirements vary by lender and by how the business is structured, and some applications need more or less.
Is the equipment the security for the loan?
Often, yes. Many equipment loans are secured over the item being financed. Some lenders may also ask for additional security or a guarantee depending on the amount, the asset and the business. Security requirements depend on the lender and product.
Can a new business get equipment finance?
Some lenders will consider newer businesses, especially with a deposit, strong personal credit and evidence of work or contracts. Options are generally narrower than for established businesses. Approval depends on lender policy, serviceability and the overall application.
Chattel mortgage or hire purchase: which is better?
Neither is better in every case. They differ in who holds title during the term and in how tax and GST are treated, and the right answer depends on the business. Speak with your accountant about tax outcomes, and with us about which structures lenders will offer.
Does equipment finance have to be for a Melbourne business?
No. We arrange equipment finance for businesses across Victoria and Australia-wide. The business just needs to meet the lender’s criteria, regardless of whether it is based in the city, a regional centre or interstate.
What can I finance besides machinery?
Depending on the lender, equipment finance can cover work vehicles and trailers, tools and attachments, technology, fit-out and some installation costs. Eligibility depends on the product, the asset and how it is used in the business.
Tradie Finance operates under Australian Credit Licence 506065 (Five Tees Pty Ltd). Lending is subject to approval, lending criteria, terms, conditions and fees. Information on this page is general in nature and does not take your circumstances into account. Tax, GST and accounting outcomes depend on your circumstances; confirm your position with your accountant.
Written and reviewed by the Finance Director at Tradie Finance