Quick answer: Concrete pump finance lets you buy a trailer-mounted line pump or a truck-mounted boom pump and spread the cost over a set term instead of tying up cash. Most concreting and civil businesses use a chattel mortgage or equipment loan, often with a balloon to keep repayments lower. You can finance line pumps, small boom trucks and large multi-axle boom pumps — new or used, low-doc or full-doc depending on your paperwork. Built for tradies, but we finance everyone.
Who concrete pump finance is for
Concreting contractors, civil pumping operators and boom-pump owner-operators who want their own gear on site instead of hiring by the pour. It also suits subcontractors bidding on bigger jobs — having your own pump means you can quote pours you’d otherwise have to sub out, and keep the margin. Whether you’ve held an ABN for years or you’re just getting the business off the ground, there’s usually a finance path. And it’s not just concreters: civil contractors, precasters and even some landscaping businesses finance pumps through us too.
What you can finance
- Trailer-mounted line pumps — the entry point for most smaller concreting businesses, new or used.
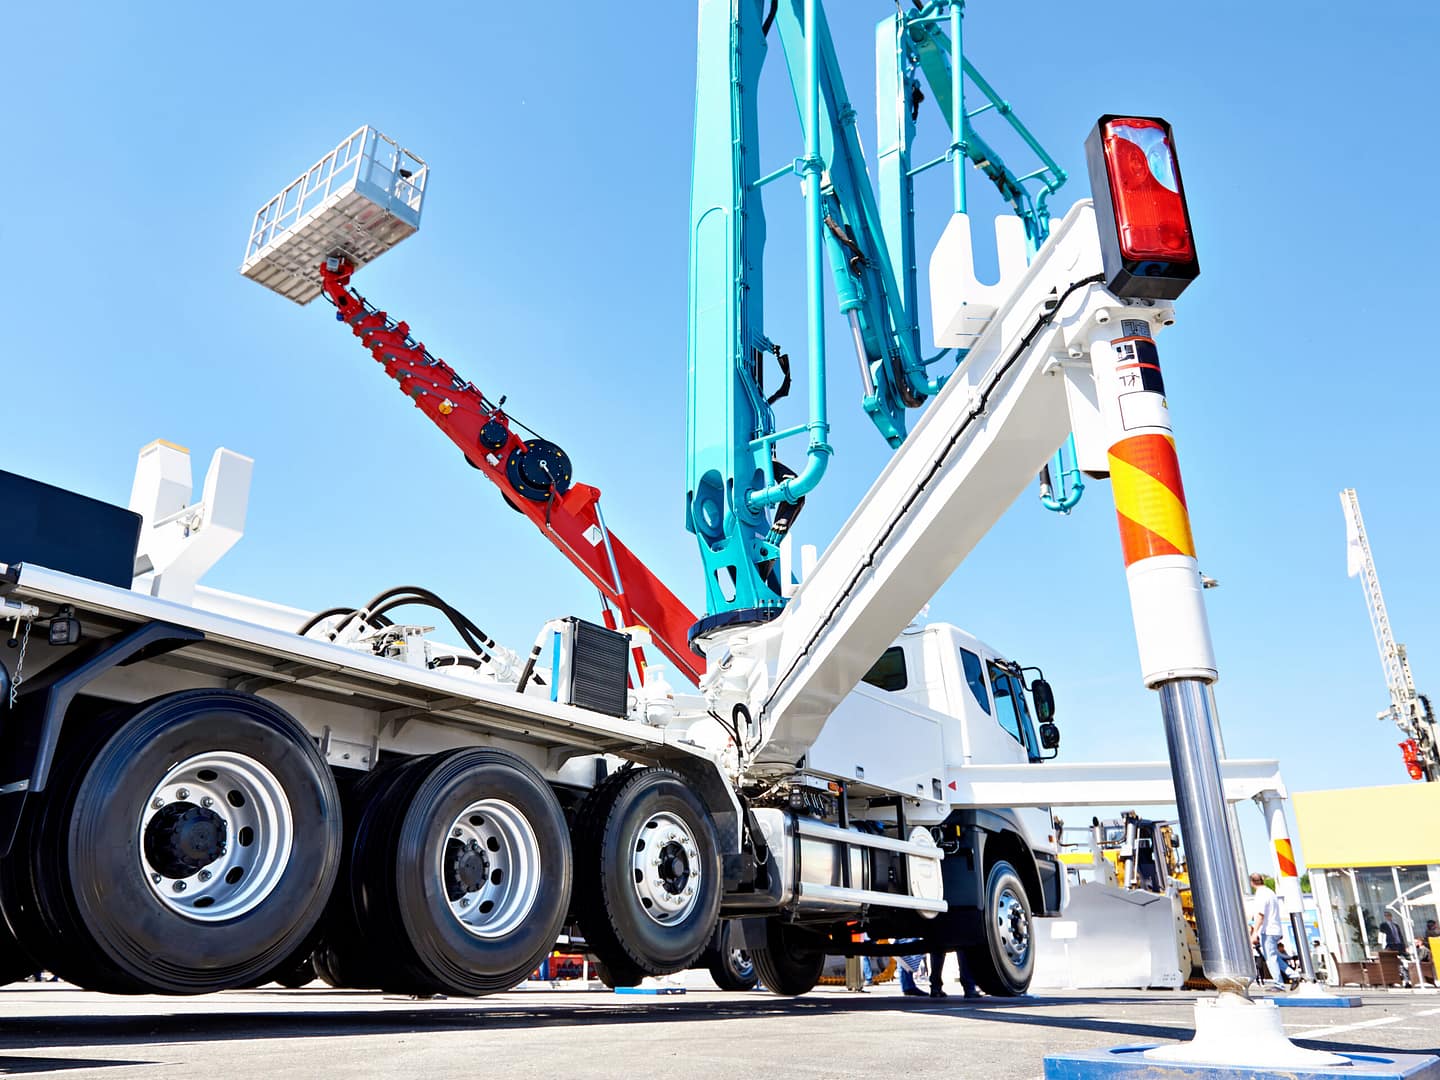
- Truck-mounted boom pumps — from compact 17–24 metre boom trucks up to 32–62 metre multi-axle units.
- Used and refurbished pumps — private sale or dealer; older units can still be financed, though term and deposit may adjust with age and hours.
- Hose, reducer and remote-control add-ons bundled into the one facility where it makes sense.
How concrete pump finance works
Most pumps are financed with a chattel mortgage (the business owns the asset from day one and the lender takes security over it) or a straightforward equipment loan. You pick a term — commonly 3 to 7 years — and you can add a balloon (a lump sum at the end) to bring weekly repayments down. Because the pump is the security, rates for commercial asset finance are typically sharper than an unsecured loan.
Want a ballpark before you talk to anyone? Run the numbers on our equipment finance calculator — set the amount, term and balloon and it estimates your weekly, fortnightly and monthly repayment in seconds. It’s an estimate, not a quote — but it’s a good starting point.
Example scenario
A concreting contractor buys a used 32-metre boom pump for $180,000 on a 5-year chattel mortgage with a 20% balloon. The balloon keeps the regular repayment lower through the term, then they either pay it out, refinance it, or trade the unit in on a bigger boom as the business grows. The exact figure depends on the lender, your profile and the machine — a broker matches you to the right one rather than you chasing banks one at a time.
New ABN or low-doc? Still worth a call
Two things concreters worry about most: not enough trading history, and not enough paperwork. Neither is an automatic no.
- New ABN: some lenders fund newly-registered businesses, especially when you’ve got trade experience or a deposit.
- Low-doc: if your financials aren’t up to date, low-doc options can use bank statements, BAS or asset position instead of full tax returns.
We’ll tell you honestly where you stand and what will strengthen the application — that’s the point of using a broker.
Why finance a concrete pump instead of paying cash
- Keeps working capital free for wages, materials and the next job.
- Potential tax benefits on business-use asset finance — check with your accountant as it depends on your structure.
- Lets you take on bigger pours and bigger contracts sooner instead of waiting to save or hiring a pump by the job.
Concrete pump finance FAQs
Can I finance a used concrete pump?
Yes. Used line pumps and boom pumps are financed every day, including private-sale units. Age and hours can affect the maximum term and the deposit a lender wants, but a well-maintained used pump is a normal, fundable asset. A broker will match the machine to a lender comfortable with its age.
Can I get concrete pump finance with a new ABN?
Often, yes. Some lenders fund new ABN holders, particularly if you have relevant trade experience, a deposit, or a strong asset position. It’s assessed case by case and subject to lender approval — the fastest way to know is to ask us for a read on your situation.
What term can I get on concrete pump finance?
Terms commonly run from 3 to 7 years. A longer term lowers each repayment; a shorter term saves interest overall. Adding a balloon reduces the regular repayment but leaves a lump sum owing at the end. The right mix depends on your cash flow and how long you’ll keep the pump.
Do I need a deposit?
Not always. Many commercial asset finance facilities are available with no deposit, subject to approval. A deposit or trade-in can help with a newer ABN, an older unit, or to reduce the amount financed. We’ll tell you what genuinely helps your application.
How much will my repayments be?
That depends on the price, term, balloon, rate and your profile, so we don’t quote a guaranteed figure up front. For an indicative estimate, use our equipment finance calculator, then speak to us for a real assessment.
Get your concrete pump working sooner. Fast approvals, less paperwork, and a finance package built around your job — not the bank’s.
Written and reviewed by the Finance Director at Tradie Finance.
This article is general information only and does not constitute credit or financial advice. Tradie Finance operates under Australian Credit Licence 506065 (Five Tees Pty Ltd). Lending is subject to approval, lending criteria, terms, conditions and fees. Estimates are indicative only and not a quote or an offer of finance.